Inspiring Adventure

on Wednesday, August 10, 2011


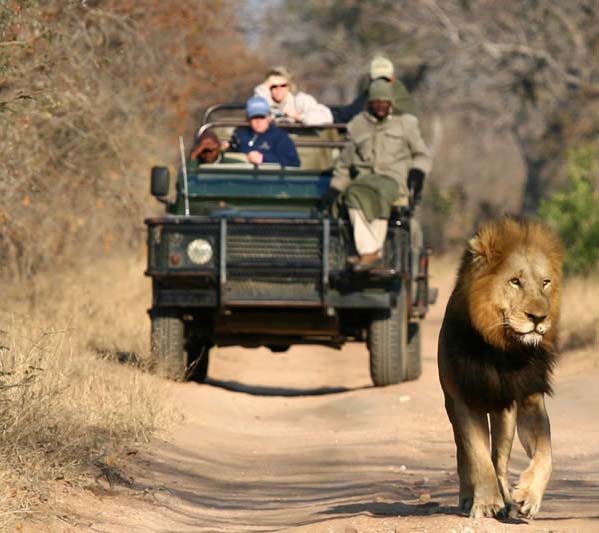
Adventure travel encourages you to stretch your mind or your body--and often both--while having a wonderful time. It doesn't matter whether you are hiking up a 14,000-foot-high mountain in Colorado, swimming with dolphins in the Caribbean or floating over an African veld in a hot air balloon. What counts is the new ways you are seeing the world, making friends in foreign places and how you are pursuing your own definition of adventure travel.


Adventure Photos:

The debt of the United States is nothing to worry about

on Wednesday, August 3, 2011

The debt of the United States government is not a problem. Compare the following graphs, one of the assets of the United States, and the other of its liabilities. As you can see, both are growing in tandem, and the nation owes about half of what it owns. This is equivalent to a man with a net worth of $50,000 having a mortgage on a $25,000 house. His payments would be $120.36 per month. (Currently, Uncle Sam must pay 4.07% on his long-term debt.) Hardly an irresponsible situation.


The total assets of the Unites States currently total about $185 trillion. The US government currently "earns" about $3 trillion per year (tax receipts), and owes about $14 trillion. Imagine a wealthy man, who owns $185 million in real estate, stocks, bonds, gold and cash, who earns an additional $3 million per year from his businesses, and owes $14 million in outstanding real estate debt. Further, imagine that he has a tremendously low interest rate on that debt (4.07%) and that he is easily able to get a loan from any bank in the world because his credit rating is so high, and he has never been late on a payment in his entire life. This is the financial situation of the US government.

But even this is not the whole picture, because the government owes a large amount of the $14 trillion debt to itself, and to quasi-governmental agencies like the Federal Reserve, and the Social Security Trust Fund.

So, not only does this very wealthy man owe a small amount when compared to his assets, it turns out that he owes a good amount to himself ($6 trillion to the Fed and other government agencies). It's as if one of his companies issued bonds that were purchased by another of his own companies.

If we continue to think about the situation, we should realize that a man owing money to himself is somewhat of a non-issue. Further, around half of the money the United States government owes is to its own citizens, which is a bit like a father owing money to his own young children. The father always has the power to confiscate 100% of the income and assets "owned" by his children, which is also the case with the US government. If push comes to shove, Sam can simply take what he needs to pay his debts, but as we have seen above, there should be little doubt in anyone's mind that he'll be able to keep his promises without resorting to extreme confiscatory policy.


Ownership of U.S Treasury Securities


Additionally, there is much talk about social security "running out of money" soon, and being unable to pay its debts. If you take a look at its history, there is little reason to think this might be the case. If anything, the danger is that the trust fund will accumulate too much excess funding. It currently holds $2.6 trillion in assets that it will use to pay its debts, and has very rarely paid out more than it received over its entire history. The basis of this nonsensical fear is precisely that the US government owes money to itself, and most of those contemplating the situation fail to consider its true nature. It is as if one company owned by the wealthy man has issued bonds, and another owns them, and sells them on the open market in order to fund its liabilities. They forget that those bonds hold real value, as demonstrated by the willingness of the public to purchase them when one of the companies offers them for sale.

It is a mistake to think of the bonds held by the Social Security Administration simply as "debts of the United States." Those bonds are salable assets, and the total quantity of their issue is a known and widely published fact. When the bonds are offered for sale by the SSA, it isn't as if the market reacts to the offering as though the bonds have materialized from thin air. On the contrary, when the SSA trades the bonds for dollars, and subsequently hands those dollars to retired citizens of the United States, the market doesn't (and shouldn't) react in any way that is different than a hedge fund offering the same assets for sale. Those bonds have been issued, and are now distinct pieces of wealth. They happen to be debts of the US government, but there is little difference between the SSA holding $2.6 trillion in government bonds, $2.6 trillion in corporate bonds, or 1.6 billion ounces of pure gold. They are all assets, and all of them can be converted via the open market to cash.

Who protects the consumer?

on Sunday, July 31, 2011

There is also a free-rider problem in the negative sense on government provision of information, because people who have no use for that information are required to pay for it. -Milton Friedman 1980

Banking: A picture book

on Saturday, July 30, 2011


COMMODITY MONEY:
The worker pans for gold, and the banker's building is empty. The banker holds no gold and no assets other than his building:
The worker wants money, so he gives the raw gold to the banker:

Who takes the raw gold:


Turns it into gold coins:

And returns the coins to the worker:

This is the process of making "commodity money." Now the banker has an empty vault again:


What happens if the worker wants paper money? He gives the gold coins back to the banker:


Who accepts them:

And holds them in his vault:
He prints up some new paper money:
And gives the notes to the worker:
He agrees to exchange the gold for the paper at any time, and the worker uses the money instead of carrying all of those heavy coins around:


FRACTIONAL RESERVE BANKING WITH A GOLD STANDARD:
What happens if the worker owns a car, free and clear, and wants to turn it into paper money, just like raw gold? The basic process is the same, except that the car is not first converted into small pieces. The worker gives the banker his car and its title:


The banker accepts ownership of the car, just like he previously accepted raw gold. Instead of weighing gold, he judges the car's value, and prints more paper money:


Now the worker has converted his car into paper money that the bank created from "thin air." The money can always be converted to gold at the bank at a fixed rate, but the banker no longer holds enough gold to redeem all the paper money; some of his assets are no longer gold. By accepting a car in exchange for paper money, the banker is engaging in "fractional reserve banking," because only a portion (fraction) of his reserves (his assets) are gold. To redeem all of the paper money, he would have to sell the car for gold. 


What happens if the worker wants to continue driving the car?


The banker loans the car to the worker. The bank now owns the car, and charges interest on the loan:


The banker also requires that the worker pay down the loan to zero over the next few years, using the paper money:


After a few years of payments, the worker has paid off the loan, and all of the notes he received in exchange for the car have been returned to the bank (plus interest):


The banker destroys the notes as they are repaid:


And returns the title to the worker:


And everything is back where it started:


Today, the process is the same, except that the paper money can no longer be exchanged for gold. It can only be exchanged for the car, by paying off the loan, but the basic process is the same as before. Today bankers convert cars and homes into paper money, instead of converting gold or silver to paper currency.

Previously, the banker agreed to redeem any note in gold or silver. Today, he'll only redeem the notes according to the bank-loan contract. Previously, anyone could redeem the notes, but today, only people with loan contracts can redeem them. If the Fed goes completely crazy tomorrow, and rampant inflation makes the notes worthless, anyone who has a car loan or a home loan can still use the worthless notes to take ownership of their home or car.

Anyone holding more outstanding bank-loan debt than they hold in cash is somewhat protected from inflation. If you have a $1 million home-loan and dollars are suddenly worthless tomorrow, you can exchange a wheelbarrow filled with worthless dollars for a $1 million home. Inflation works in your favor if you hold loan agreements denominated in dollars.

NOTE: A bank doesn't loan out notes it holds in checking accounts. Each bank loan generates new money from thin air. The bank may invest the gold or car (its assets) in very safe investments, but new loans always create new money. New dollars are exchanged for real assets. Checking accounts are not bank equity; they are not owned by the bank. The bank is providing a holding service, like a bank that accepts gold coins and agrees to guard them for a fee.

NOTE 2: Astute readers (or those who have seen the Zeitgeist movie too many times) may wonder how, absent the gold standard, workers can pay back more dollars than they originally accept. How can there be enough dollars in the world to pay the interest on the loan? The answer is that the banker prints up some "fake" notes and spends them. His goal is to print up just enough notes so that the the man can repay his loan. Today this process is known as "Quantitative Easing." The Fed literally prints money from thin air and spends it, usually purchasing government bonds with the "fake" new money. Banks are  compensated for their work in this way. The interest on bank loans is an investment activity not unique to banking -- anyone can loan their assets at interest. Bankers are specifically compensated for the service of turning assets into paper money when they print and spend "fake" dollars -- dollars that are not exchanged for real assets, but are simply printed and spent.

NOTE 3: Printing "fake" dollars does not create inflation, per se, because the new money that bankers create through the loan process is worth more than the original asset. Ask yourself, would you rather be paid $10,000 in cash, or paid with a car that recently sold for $10,000? The reason you would choose the currency is because of its liquidity. It is easy to spend the money, and easy to buy bread and milk with it, and everyone will accept it. A car is much harder to exchange, even though it is "worth" the same amount. The money's liquidity makes it worth more than the car, and the banker's fake notes offset this by increasing the supply of currency.


Middle-Class Stagnation Case-Study: Housing Prices

on


As you can see from the charts above, the price of an average home in 1978 was about the same as today, but the size of the average home has gone from 1,700  to 2,500 square feet. That means that the average middle-class home is today about 41% bigger, will last longer and require less money to maintain, and is exactly the same price as it was 30 years ago. The middle class is doing 41% better if we only consider the size.  If the quality of materials (roofing rated to last 50 years, plastic siding that requires no paint, high efficiency central air) and much lower maintenance are considered, the middle class is doing very well indeed compared to 1978.